Finance Act 2026 Explained: What Actually Changed for Ordinary Kenyans
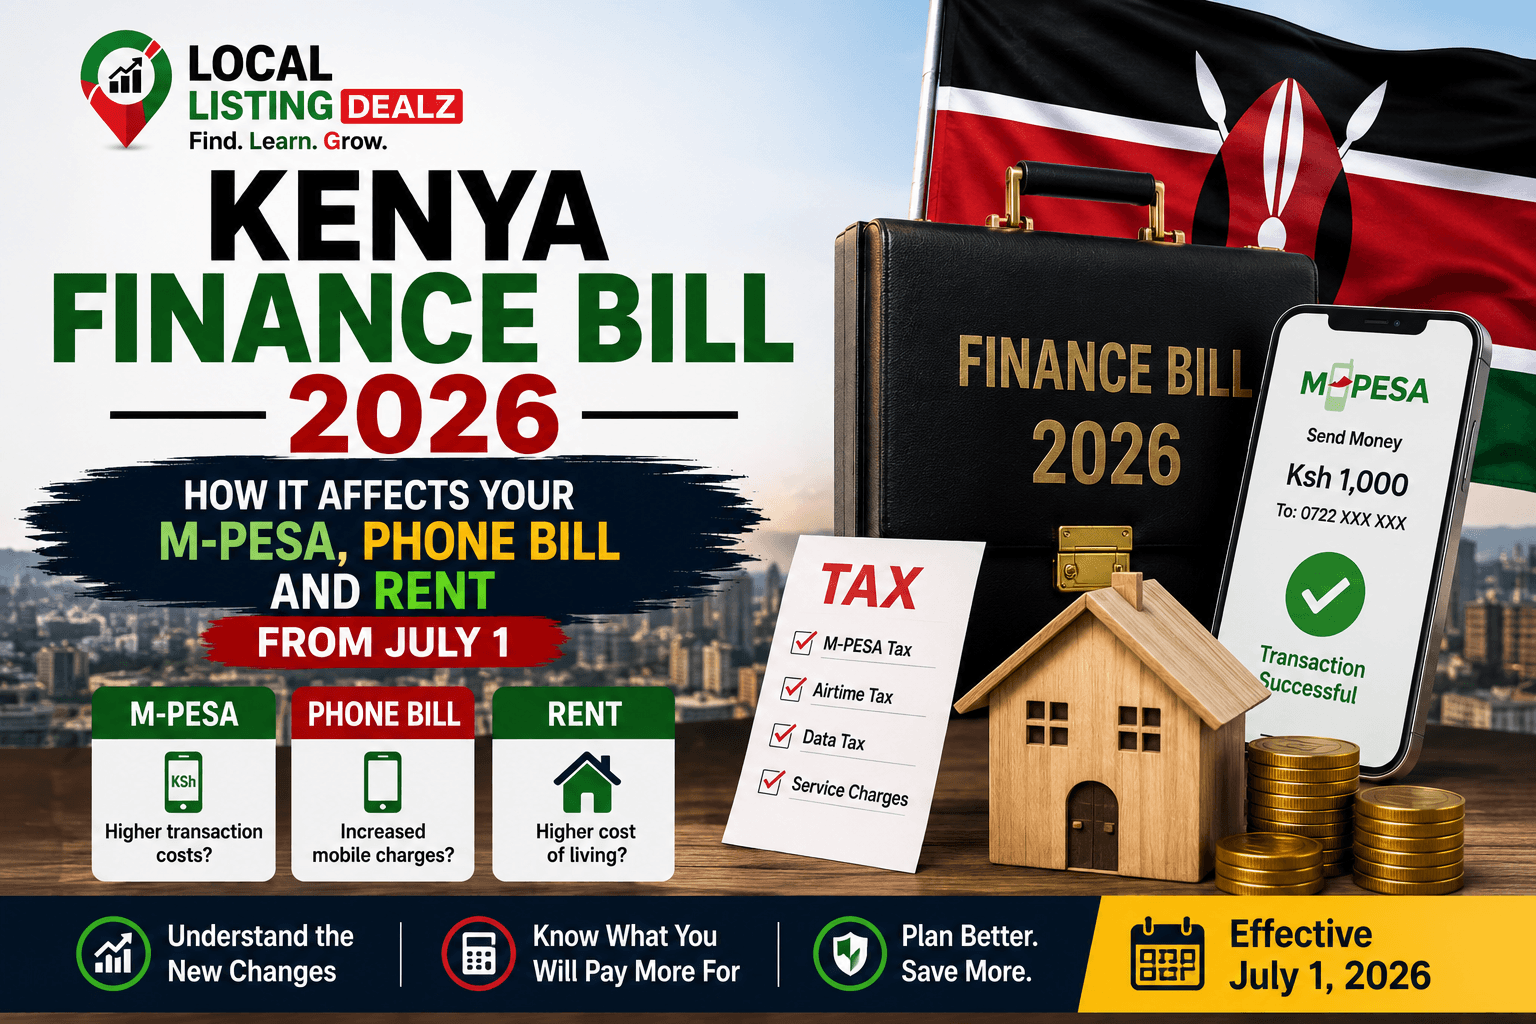
The Kenya Finance Bill 2026 is no longer a bill — President Ruto signed it into law as the Finance Act, 2026 in late June 2026, and most of its provisions took effect July 1, 2026. If you’ve been going off earlier coverage (including earlier versions of this guide), several important details changed between the original April draft and what actually became law. This guide reflects the final, enacted Act — not the proposal stage.
What Is the Finance Act 2026, and Why the Confusion?
The Finance Bill went through months of amendments between its April 30, 2026 publication and its June signing — and several provisions flipped direction more than once during that process. That’s exactly why so much of what’s circulating online (including some earlier reporting) is now wrong: it was accurate for a version of the bill that no longer exists. Here’s what’s actually in force.
Phone Tax: What Really Happened (Correction from Earlier Reporting)
Earlier coverage — including earlier drafts of this guide — described a plan to replace Kenya’s roughly 55.5% combined phone import tax with a single 25% excise duty charged at the point of activation. That specific mechanism was dropped from the final Act.
What actually happened instead: mobile phones became VAT-exempt effective July 1, 2026 — the 16% VAT that used to apply at import no longer does. The activation-based excise duty restructuring did not survive to the final law. This still means new phones are somewhat cheaper than before, but the mechanism and the scale of the saving are different from what was originally proposed — don’t expect the dramatic 55.5%-to-25% drop that was floated earlier in the year.
M-Pesa and Digital Payments: This One Did Pass
Unlike the phone tax mechanism, the digital payments tax changes went through largely as proposed. The Finance Act 2026 confirms:
- VAT on digital financial services — including money transfers and payment gateway fees — is now in force.
- Withholding tax on merchant service and card interchange fees was expanded, affecting card payments at supermarkets, restaurants, and petrol stations.
As with the original proposal, this tax applies to the fee charged for a transaction, not the amount you send. If M-Pesa charges you KES 7 to send KES 1,000, VAT now applies to that KES 7 fee — not to the KES 1,000 itself. Expect transaction costs to have moved up slightly rather than dramatically, and merchants accepting card payments may pass a small additional cost through to prices.
Rental Income Tax: The Correction That Matters Most
This is the most consequential reversal for ordinary Kenyans, and it’s the opposite of what was widely reported mid-year.
Earlier reporting said the proposed increase from 7.5% to 10% residential rental income tax had been dropped. Based on post-enactment analysis, it was not — the Finance Act 2026 increased the residential rental income tax rate from 7.5% to 10%.
If you’re a landlord earning rental income in Kenya, budget for the higher rate. Using the earlier example: a landlord collecting KES 50,000 per month (KES 600,000 annually) now pays roughly KES 5,000 per month in rental income tax rather than KES 3,750 — an increase of about KES 1,250 per month. Some landlords may pass part of this through to tenants via rent increases, though that’s a market decision, not a tax requirement.
Separately, non-resident landlords face a different, larger change. The Act introduced a self-assessment regime taxing non-resident rental income at 30% of gross rent — a meaningfully higher rate than the 10% final-tax figure reported during the bill stage. This applies specifically to foreign nationals earning rental income from Kenyan property, not to Kenyan resident landlords.
If you’re a tenant: the direct legal change applies to your landlord’s tax bill, not a new tax on you — but if your landlord raises rent to cover the higher rate, that’s the indirect way this could reach you.
Other Confirmed Changes in the Finance Act 2026
A few provisions weren’t prominent in earlier bill-stage coverage but are now part of the law:
- Betting and lottery winnings: A 20% withholding tax on winnings from betting, lotteries, and prize competitions was reintroduced.
- Scrap metal sales: A 1.5% withholding tax now applies to gross scrap metal sales.
- Pre-populated tax returns: KRA is now empowered to use automated systems and e-TIMS data to generate pre-filled tax returns for taxpayers — intended to simplify filing, though it also means KRA has more visibility into your transaction data by default.
- Strengthened KRA enforcement: The Act expands KRA’s powers around agency notices during dispute objections, giving the authority more leverage during tax disputes.
- Export declaration regime (business-relevant): Effective September 1, 2026, importers must obtain and retain export declarations for five years. This is a compliance matter primarily affecting import-dependent businesses rather than individual consumers.
What Was Confirmed as Dropped
A few of the original bill’s more aggressive proposals did not make it into the final Act:
- The activation-based mobile phone excise duty (replaced by the VAT exemption approach described above)
- A proposed deemed dividend tax on undistributed company profits
- Removal of East African Community excise preferences
- The mitumba (second-hand clothing) import tax increase
- A proposed one-month nil-return filing rule
Tax Amnesty and Filing Deadlines — Still in Force
Two provisions from the original bill made it through unchanged:
Tax amnesty: If you or your business has outstanding KRA penalties or interest on liabilities from periods up to December 31, 2025, the amnesty remains available — provided the underlying principal tax is settled by December 31, 2026.
Filing deadline change: Income tax return filing deadlines shift from six months to four months after year-end — but this specific change doesn’t take effect until January 1, 2027, not immediately. For an individual on a standard December 31 year-end, this means your 2026 return (filed in 2027) will be due earlier than you’re used to. You have one more filing cycle at the old deadline before this applies.
What Takes Effect When — Updated Status Table
| Change | What It Means for You | Status | Effective Date |
|---|---|---|---|
| Mobile phones VAT-exempt | Modest reduction in new phone prices | ✅ In force | July 1, 2026 |
| Activation-based phone excise duty | Did not happen — dropped from final Act | ❌ Dropped | N/A |
| VAT on digital payment/M-Pesa fees | Transaction fees have risen slightly | ✅ In force | July 1, 2026 |
| Card interchange withholding tax | Marginal upward pressure on card-accepting merchants | ✅ In force | July 1, 2026 |
| Residential rental income tax 7.5% → 10% | Kenyan landlords now pay the higher rate | ✅ In force (reverses earlier “dropped” reports) | July 1, 2026 |
| Non-resident landlord tax at 30% of gross rent | Foreign property owners in Kenya | ✅ In force | July 1, 2026 |
| Betting/lottery winnings withholding tax (20%) | Applies to winnings | ✅ In force | July 1, 2026 |
| Tax amnesty (pre-Dec 2025 liabilities) | Settle old KRA debts at reduced cost | ✅ In force | Through Dec 31, 2026 |
| Filing deadline: 6 months → 4 months | Returns due earlier each year | ✅ In force | January 1, 2027 |
| Mitumba import tax increase | Did not happen | ❌ Dropped | N/A |
Frequently Asked Questions
Is the Kenya Finance Bill 2026 now law? Yes. It was signed by President Ruto in late June 2026 and is now the Finance Act, 2026. Most provisions took effect July 1, 2026.
Did rental income tax actually go up? Yes — despite earlier reporting that this proposal was dropped, the final Finance Act 2026 increased the residential rental income tax rate from 7.5% to 10% for Kenyan resident landlords.
Did M-Pesa fees actually increase? The VAT on payment provider fees was enacted as proposed, applying to the fee charged on a transaction rather than the amount transferred. Expect a small increase in transaction costs rather than a dramatic one.
Did phones actually get cheaper? Somewhat — mobile phones became VAT-exempt from July 1, 2026, which does reduce prices. However, the more dramatic 55.5%-to-25% restructuring that was originally proposed did not make it into the final law.
When does the new filing deadline start? January 1, 2027 — not immediately. You have one more filing cycle at the current six-month deadline before the shortened four-month deadline applies.
The Plain Summary
Budget for the higher 10% rate now if you rent out property in Kenya, as this correction matters most from earlier coverage.
If you use M-Pesa or pay by card, expect transaction costs to be marginally higher than before July 2026, not dramatically so.
If you were waiting to buy a phone expecting a dramatic price drop from the activation-tax proposal, that specific mechanism didn’t happen — but the VAT exemption still helps somewhat.
And if you have old KRA penalties hanging over you, the amnesty window is open through the end of 2026 — that one’s worth acting on regardless of anything else in this Act.
Sourced from the enacted Finance Act, 2026 (assented by the President in late June 2026), and post-enactment analyses from EY, PwC, RSM, and Bowmans Kenya. This article is for informational and educational purposes only and does not constitute tax or legal advice — for decisions specific to your situation, consult a licensed tax advisor or KRA directly at itax.kra.go.ke.